

Cap Rate Calculation Guide: What to Check Before You Rely on the Result
Learn how to calculate cap rate from realistic income and expenses, test assumptions, and assess whether the result supports an Ottawa property decision.
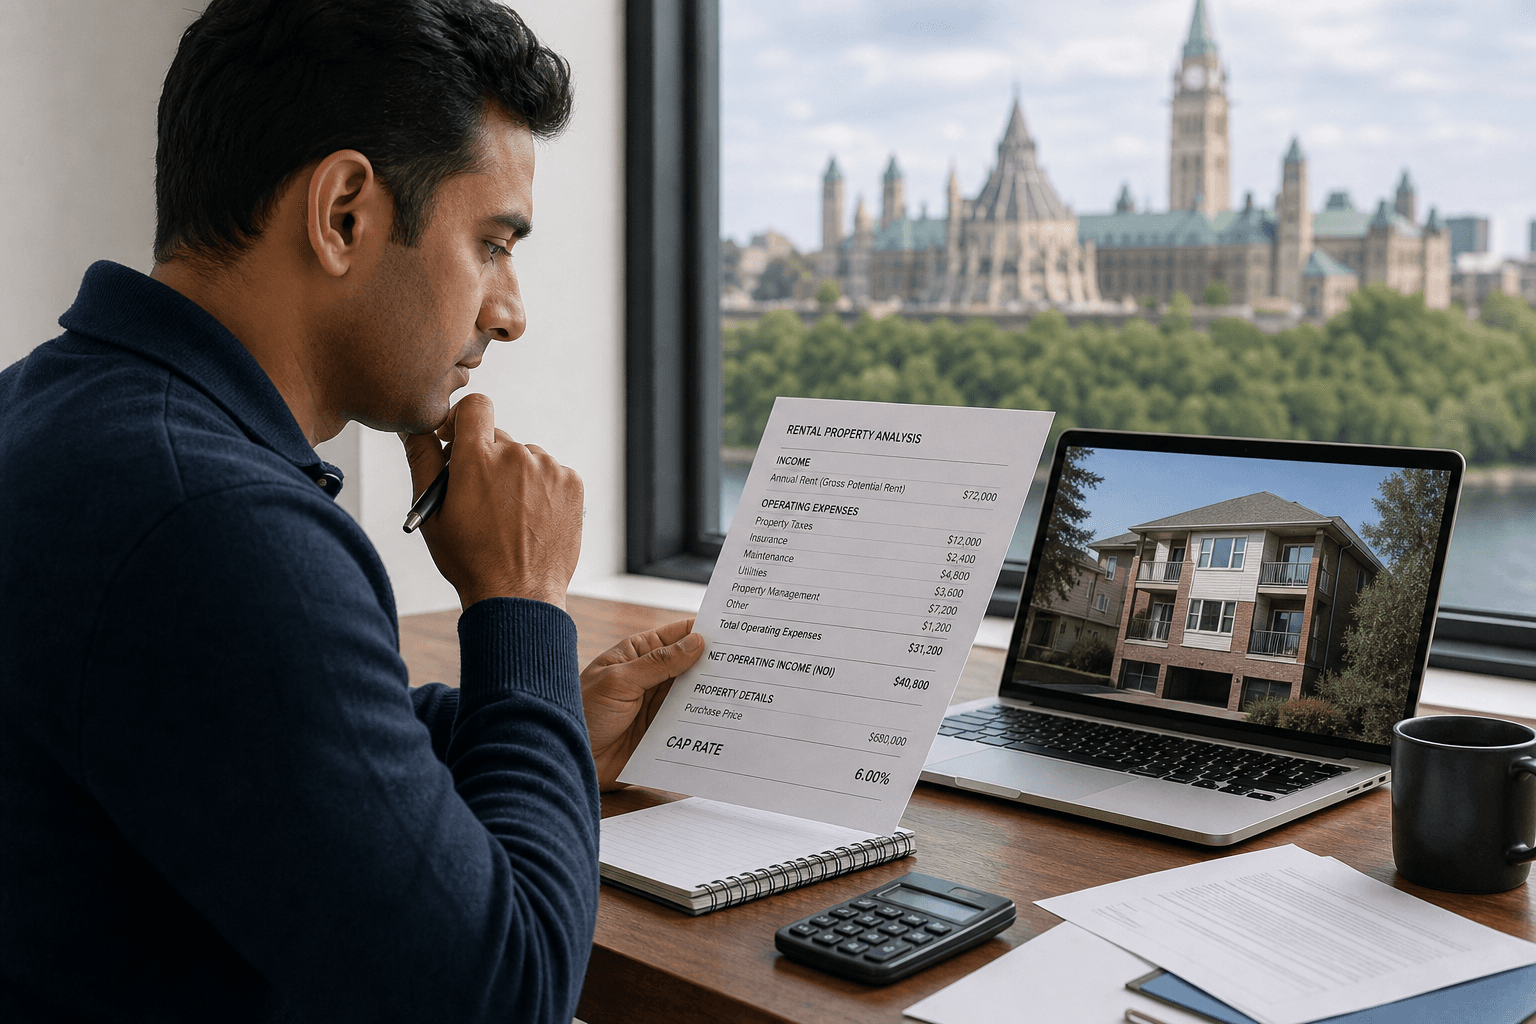
A cap rate can help you screen and compare income-producing properties, but it is not a guaranteed return or a complete investment analysis. The result is only as useful as the net operating income, vacancy assumptions, expenses, and property value used in the calculation.
This cap rate calculation guide explains the formula, shows a hypothetical example, identifies common mistakes, and provides a pre-offer checklist for residential rental and commercial properties in Ottawa.
What cap rate measures, and what it does not
Capitalization rate, usually called cap rate, is a property-level measure that relates a property's annual net operating income to its current market value or purchase price. The Canada Mortgage and Housing Corporation describes cap rate as a metric for assessing a property's return on investment and distinguishes it from cash-on-cash return, which assesses an investment from a different perspective.
In practical terms, cap rate helps answer this question: “Based on the property's operating income, how does its price compare with its income-producing potential?” It can be useful when screening several rental or commercial properties, provided the figures are calculated consistently.
Cap rate does not tell you whether the property will appreciate, whether your financing will be affordable, or whether the investment will produce positive cash flow after debt payments. It also does not capture every risk associated with vacancy, major repairs, changing rents, tenant turnover, or a property's suitability for its intended use.
The cap rate formula

The basic formula is:
Cap rate = net operating income ÷ purchase price or current market value
Multiply the result by 100 to express it as a percentage. For example, an NOI of $30,000 divided by a property value of $500,000 produces a cap rate of 6%.
Use annual figures for both the numerator and denominator. If income and expenses are listed monthly, convert them to annual amounts before calculating. The denominator depends on the question you are asking. Purchase price can help assess a proposed acquisition, while current market value can help assess the property's present income yield.
How to calculate net operating income before cap rate
NOI is the property's income after normal operating expenses, but before mortgage payments and other financing costs. A reliable calculation usually follows four steps.
1. Start with realistic income and vacancy assumptions
Begin with gross scheduled rental income, meaning the income the property would produce if the units or space were rented according to the stated leases or realistic market rents. Add other recurring property income only when it is documented and reasonably expected to continue.
Then account for vacancy, turnover, concessions, and possible collection losses. A listing that assumes full occupancy indefinitely may present an income figure that is higher than the property can reliably produce. Asking rent is also not the same as collected rent, particularly when the amount has not been supported by leases, rent records, or comparable evidence.
2. Include recurring operating expenses
Subtract the costs required to operate and maintain the property. Depending on the asset, these may include property taxes, insurance, owner-paid utilities, repairs and maintenance, property management, condominium or common expenses, landscaping, snow removal, and administrative costs.
Review which expenses are paid by the owner and which are paid by tenants. In a commercial property, the lease structure may allocate certain costs differently than a typical residential rental. Omitting a recurring expense increases NOI on paper and makes the cap rate appear stronger than it may be in practice.
3. Work through the calculation
The following is a hypothetical example using invented figures. It is not an Ottawa market benchmark, a client result, or a forecast for any particular property.
| Item | Annual amount |
|---|---|
| Gross scheduled rent | $42,000 |
| Other recurring income | $1,000 |
| Less: vacancy and collection allowance | -$2,150 |
| Effective gross income | $40,850 |
| Operating expenses | -$10,850 |
| Net operating income | $30,000 |
If the hypothetical purchase price is $500,000, the calculation is $30,000 ÷ $500,000 = 0.06, or a 6% cap rate. That percentage is a screening result based on the assumptions shown. It is not a promise that the property will produce a 6% cash return after financing, taxes, capital improvements, or other investor-specific costs.
Calculation mistakes that can distort the result
Using gross rent instead of NOI
Dividing gross rent by the purchase price produces a gross yield-like figure, not a cap rate. It ignores the cost of operating the property, so two properties with the same rent and price could appear identical even if one has much higher taxes, insurance, maintenance, or management costs.
Always identify the income figure, list the deductions, and confirm that the final number is NOI before applying the cap rate formula.
Assuming full occupancy
A zero-vacancy assumption can overstate income when a property has regular turnover, leasing delays, concessions, or collection concerns. Residential investors should consider unit turnover and tenant changes. Commercial buyers should examine lease expiries, renewal risk, tenant concentration, and the time required to re-lease specialized space.
The appropriate assumption depends on the property and available evidence. The important point is to make the assumption visible and test what happens if occupancy is lower than projected.
Leaving out recurring or deferred costs
Some calculations omit expenses because they are not shown in a listing or because the current owner handles them informally. That does not make the costs disappear. Verify taxes, insurance, utilities, management, maintenance, common expenses, and any services required to keep the property operating.
Also separate normal operating expenses from major capital items such as a roof, heating system, windows, or substantial renovations. A capital item may not be treated the same way as a recurring expense in every analysis, but it still affects the money required to own and maintain the property. A strong-looking cap rate does not remove the need to investigate deferred maintenance.
Treating projections as established results
Projected rent, future occupancy, and estimated expenses should be labelled as assumptions, not historical performance. Ask what supports each projection and whether it depends on renovations, a different tenant profile, a change in use, or a rent increase that has not yet occurred.
Useful documents may include current leases, a rent roll, payment history, utility bills, tax information, insurance details, maintenance records, and operating statements. The exact documents available will vary by property and transaction.
Confusing cap rate with mortgage-based return
Mortgage payments are generally considered separately from property-level NOI when comparing cap rates. This keeps the cap rate focused on the property's operating performance rather than the financing structure chosen by one buyer.
After calculating NOI and cap rate, review debt payments, required equity, financing costs, and resulting cash flow separately. Cash-on-cash return considers the cash invested and the cash generated after relevant financing effects. It should not be treated as interchangeable with cap rate.
Cap rate versus the other numbers investors need
Each metric answers a different question. Using several of them reduces the risk of making a decision from one attractive-looking percentage.
| Metric | What it shows | Decision it supports |
|---|---|---|
| Gross income | Scheduled property income before deductions | Whether the income story is worth investigating |
| Operating expenses | Recurring costs required to operate the property | Whether the income estimate is realistic |
| NOI | Income after operating expenses, before financing | Property-level operating performance |
| Cap rate | NOI relative to price or current value | Comparing income-producing properties |
| Cash flow | Money remaining after relevant expenses and debt payments | Assessing affordability and ongoing cash requirements |
| Cash-on-cash return | Cash return relative to invested cash | Assessing the effect of equity and financing |
| Property valuation | An opinion or analysis of value using relevant property evidence | Testing whether the proposed price is reasonable |
For residential investments, combine the cap rate with a property evaluation that considers condition, renovation needs, and investment insight. A cap rate may look acceptable until required work, tenant turnover, or realistic rent assumptions are included.
How to interpret cap rate without treating it as a verdict
There is no single cap rate that automatically makes every property a good or bad investment. A higher apparent rate may reflect greater maintenance needs, weaker income durability, a less suitable location, more vacancy risk, or a price that requires careful investigation. A lower rate may accompany stronger income stability or a different risk profile, but the percentage alone cannot establish that.
Compare properties using consistent assumptions and ask what is driving the difference. Is the variation caused by rent, expenses, condition, tenant quality, lease terms, building systems, or the asking price? Those questions are more useful than treating the cap rate as a pass-or-fail score.
Residential rental properties: check condition and income durability
For a home, condo, or other residential rental, review the condition of the unit and building alongside the income statement. Repairs, renovations, appliance replacement, condominium expenses, insurance, and tenant turnover can materially affect the amount available to an owner.
Be cautious when a calculation depends on rent that requires improvements or on an occupancy level that the property has not demonstrated. A realistic residential analysis should show what happens when rent is lower, vacancy is higher, or maintenance costs exceed the initial estimate.
Commercial properties: look beyond the headline rate
Commercial properties require additional attention to lease structure, tenant obligations, renewal dates, operational requirements, and the suitability of the space for its intended use. A cap rate does not reveal whether a warehouse, industrial unit, retail location, or office space supports the tenant's workflow.
When assessing an income-producing commercial property, commercial real estate solutions can add context to the cap rate by accounting for operational requirements, layout efficiency, and building systems. These factors may affect tenant demand, operating costs, and the durability of the income assumption.
If you are also reviewing mortgage options, understand how the financing structure changes your cash flow rather than changing the property's underlying NOI. A general comparison of fixed and variable mortgage rates may help frame that separate financing question, but it does not replace property-specific lending advice.
Pre-offer cap rate checklist
- Income evidence: Have you reviewed leases, a rent roll, payment history, and the basis for any projected rent?
- Vacancy: Does the analysis allow for turnover, leasing time, concessions, and possible collection losses?
- Expenses: Are taxes, insurance, utilities, management, maintenance, common expenses, and other recurring costs included?
- Property condition: Are there known repairs, renovations, deferred maintenance, or building-system concerns?
- Value: Are you dividing NOI by the proposed purchase price, current market value, or another clearly stated denominator?
- Financing: Have you reviewed debt payments, required equity, and cash flow separately from cap rate?
- Sensitivity: Have you tested lower rent, higher vacancy, increased expenses, and an unexpected repair?
- Professional review: Do you need qualified legal, tax, accounting, lending, building, or real estate advice before relying on the analysis?
Test what happens when assumptions change
A sensitivity test changes one or more assumptions to see which inputs control the result. For example, recalculate the hypothetical example with lower rent, a larger vacancy allowance, higher insurance, increased maintenance, or a different purchase price.
If a small change produces a large difference in NOI or cap rate, that assumption deserves particular verification. Sensitivity testing does not predict the future, but it shows whether the decision depends on a narrow set of optimistic figures.
Frequently asked questions
Does cap rate include mortgage payments?
Generally, no. Cap rate is normally based on NOI before financing costs. Mortgage payments should be reviewed separately when calculating cash flow and cash-on-cash return.
What is the difference between cap rate and cash-on-cash return?
Cap rate relates property-level NOI to property value or purchase price. Cash-on-cash return considers the cash invested and the cash produced after relevant financing effects. They answer different questions and can produce different results for the same property.
Should I use purchase price or current market value?
Use the denominator that matches your decision and state it clearly. Purchase price is useful when assessing a proposed acquisition. Current market value can be useful when assessing the property's present income yield or comparing it with other assets.
How do vacancy and repairs affect a property's cap rate?
Vacancy reduces effective income, while operating expenses and necessary work reduce the income available after costs. If either is omitted or understated, NOI and the resulting cap rate may be overstated.
Can cap rate alone tell me whether an Ottawa investment property is a good buy?
No. Cap rate is a screening and comparison tool. A decision should also consider verified income, expenses, condition, value, financing, tenant or lease risk, and how the result changes under less favourable assumptions.
Use cap rate as a starting point, not the whole decision
A dependable cap rate calculation begins with realistic income, a visible vacancy allowance, complete operating expenses, and a clearly stated property value or purchase price. The result becomes more useful when you test the assumptions and compare it with cash flow, cash-on-cash return, property condition, and valuation evidence.
For an Ottawa residential or commercial investment, the most responsible next step is to verify the numbers before relying on the headline rate. Sagar Shah Real Estate provides Ottawa residential and commercial real estate services, including property valuation and investment analysis, with technical insight and sales expertise to support buying, selling, leasing, and property decisions. Visit Sagar Shah Real Estate to discuss the property and the analysis it requires.
Ready to discuss your real estate goals?
Get practical, personalized guidance for your next move in Ottawa.
Book a consultation